
Mergers & Acquisitions
- October 20, 2026
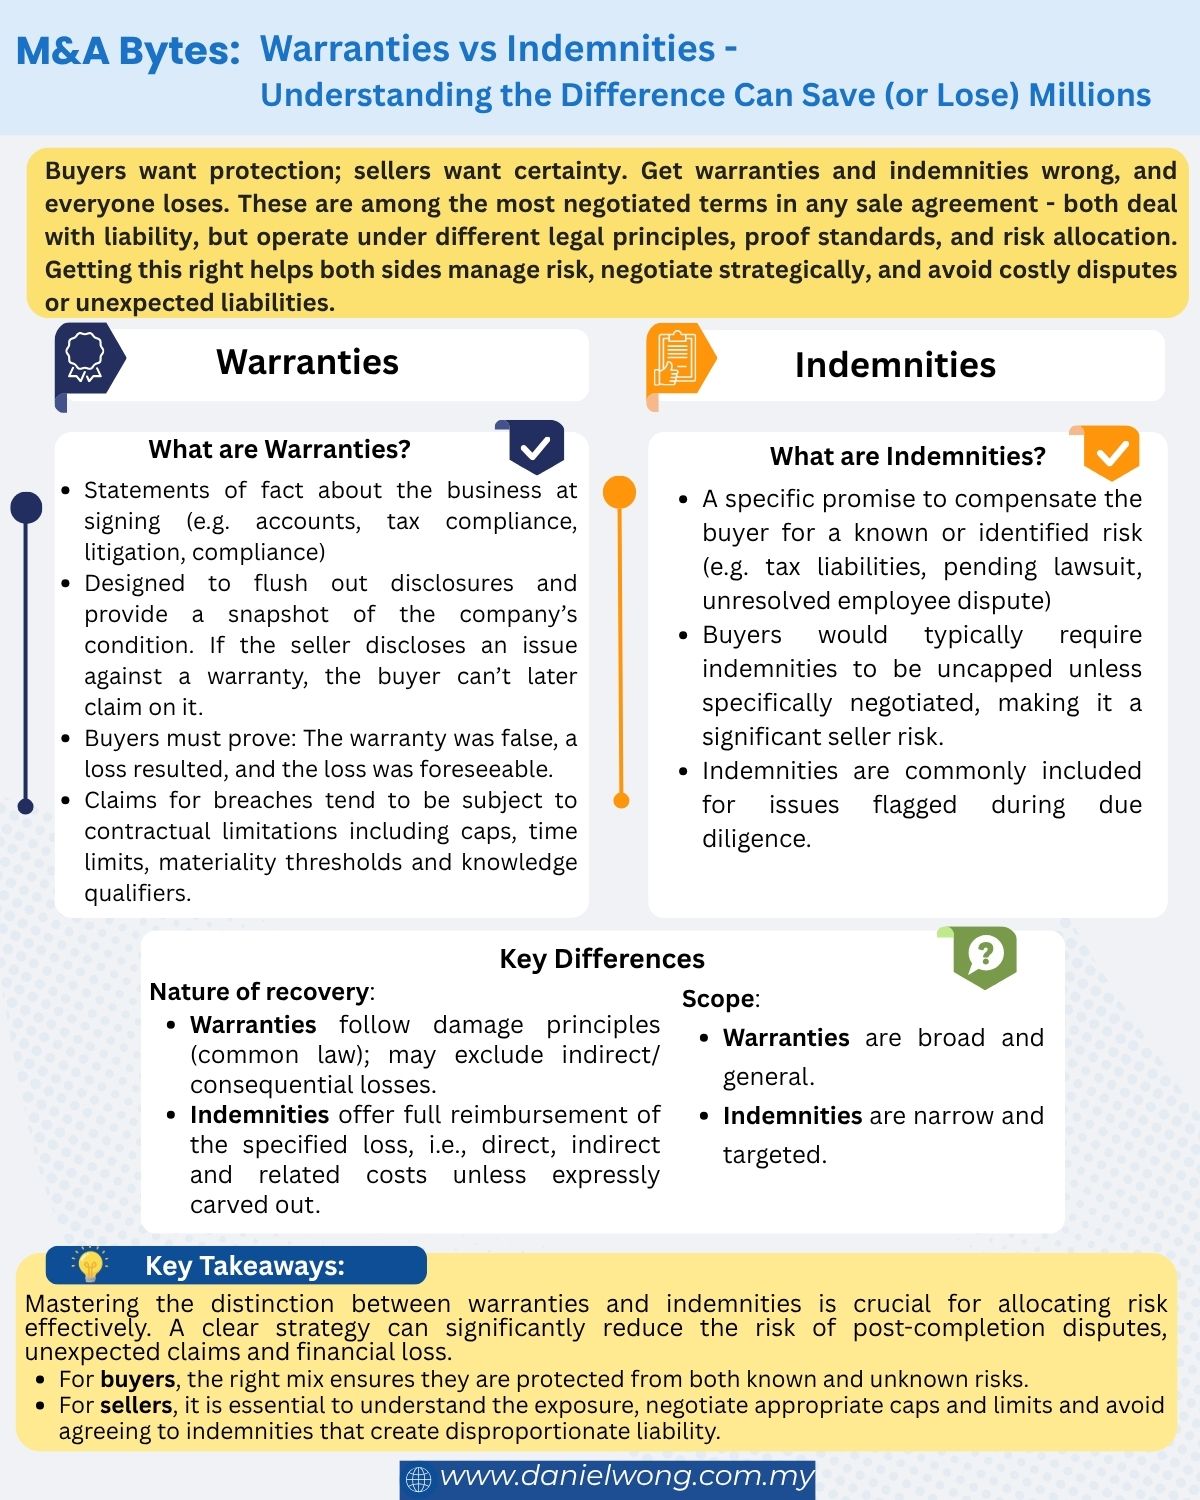
Buyers want protection; sellers want certainty – get warranties and indemnities wrong, and everyone loses.
Warranties and indemnities are among the most heavily negotiated parts of any sale and purchase agreement. While both deal with liability, they operate under different legal principles, require different levels of proof and shift risk in different ways. Understanding how warranties and indemnities work helps buyers and sellers:
- Manage and allocate transaction risk
- Negotiate protection more strategically
- Avoid costly post-completion disputes or unexpected liabilities.
What are Warranties?
- Warranties are statements of fact about the business and its condition at signing (e.g. accuracy of accounts, tax compliance, no litigation, no financing arrangements, compliance with laws)
- Warranties are designed to flush out disclosures and provide a snapshot of the company’s condition. If the seller discloses an issue against a warranty, the buyer cannot later claim for it because they accepted the risk.
- Breaches of warranties require the buyer to prove:
- the warranty was false;
- the buyer suffered a loss; and
- the loss was foreseeable.
- Claims for breaches tend to be subject to contractual limitations including caps, time limits, materiality thresholds and knowledge qualifiers.
What are Indemnities?
- Indemnities are a specific promise to compensate the buyer for a known or identified risk (e.g. tax liabilities, pending lawsuit, unresolved employee dispute)
- The buyer would typically require indemnities to be uncapped unless specifically negotiated, making indemnities a significant seller risk.
- Indemnities are commonly included for issues uncovered during due diligence.
What are the Key Differences?
- Nature of Recovery:
- Warranties – follow damage principles, which are based on common law principles and may exclude indirect or consequential losses.
- Indemnities – offer full reimbursement for the specified loss, namely direct, indirect and related costs, unless expressly carved out.
- Scope:
- Warranties – broad and general
- Indemnities – narrow and targeted
🔑 Key Takeaway:
Mastering the distinction between warranties and indemnities is crucial for allocating risk effectively.
For buyers, the right mix ensures they are protected from both known and unknown risks.
For sellers, it is essential to understand the exposure, negotiate appropriate caps and limits and avoid agreeing to indemnities that create disproportionate liability.
A clear strategy on warranties and indemnities can significantly reduce the risk of post-completion disputes, unexpected claims and financial loss.
In Essence:
Disclaimer: The content of this article is intended for general informational purposes only and does not constitute formal legal advice.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- October 6, 2026
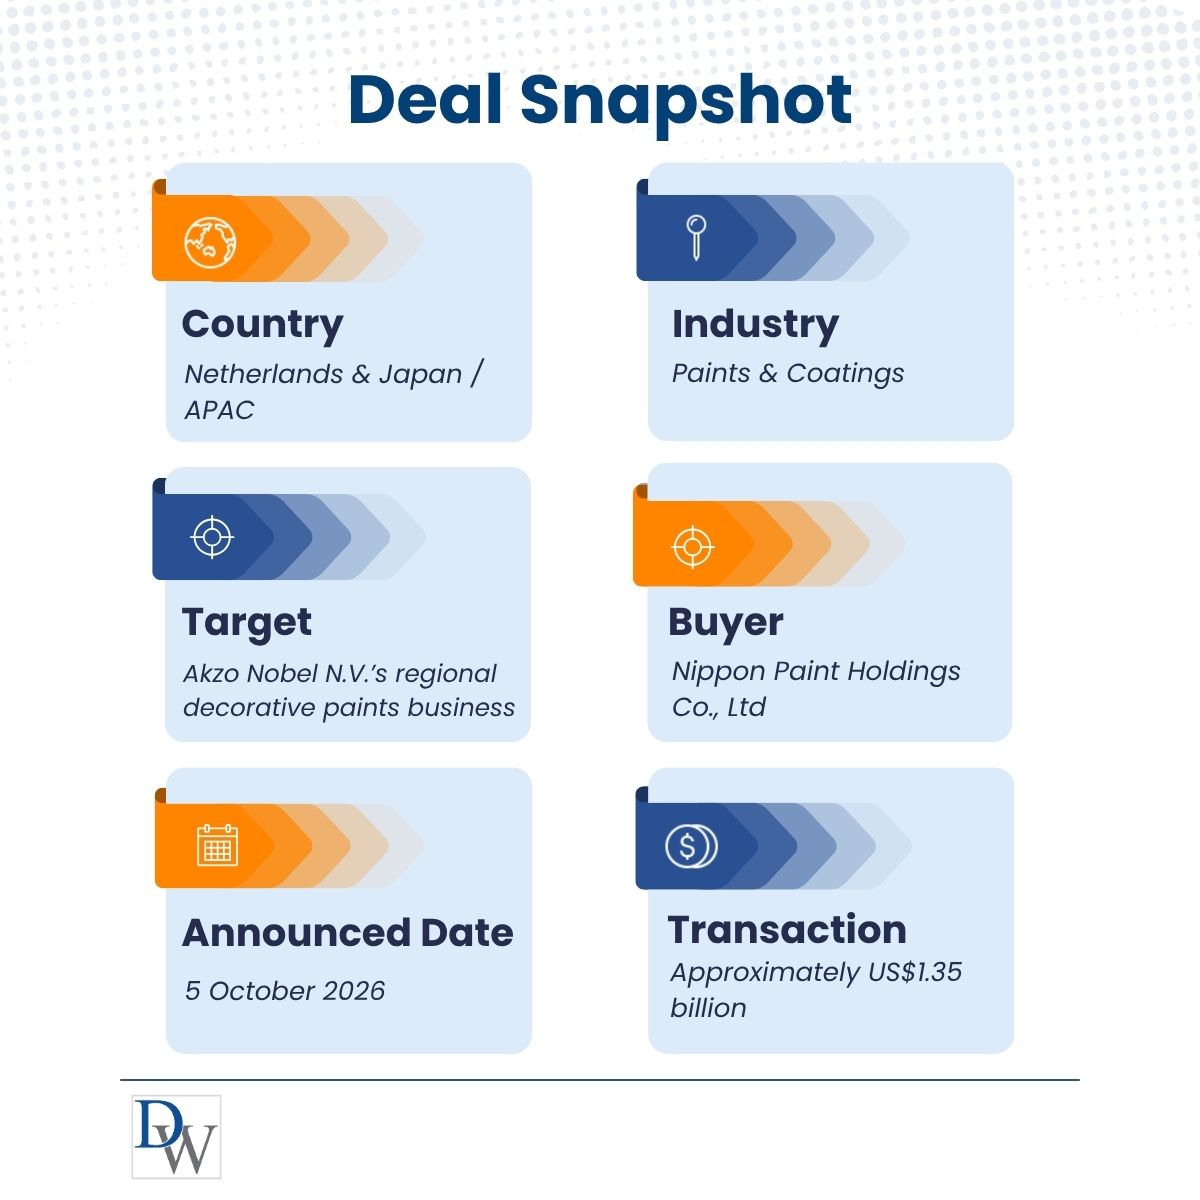
AkzoNobel has agreed to sell its decorative paints business across Southeast Asia, Australia and Papua New Guinea to Nippon Paint Holdings Co., Ltd. for approximately US$1.35 billion. The proposed divestment covers operations across seven markets – Malaysia, Singapore, Indonesia, Thailand, Vietnam, Australia and Papua New Guinea – and forms part of AkzoNobel’s broader strategy to sharpen its portfolio and focus its resources on its core paints and coatings businesses.
From a strategic standpoint, the transaction enables AkzoNobel to streamline its regional portfolio and redeploy capital towards its broader corporate priorities. For Nippon Paint, the acquisition is set to further strengthen its scale and market presence across the Asia-Pacific region by adding established decorative paints operations in markets where it already has a significant footprint.
Taken together, the transaction demonstrates how regional carve-outs can serve different strategic objectives for each side of an M&A deal – enabling sellers to reshape their portfolios while allowing buyers to selectively expand their geographic reach and market position.
🌏 Our Global Deal Radar series highlights major M&A deals and corporate transactions shaping industries worldwide. Follow us for monthly insights.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- September 22, 2026
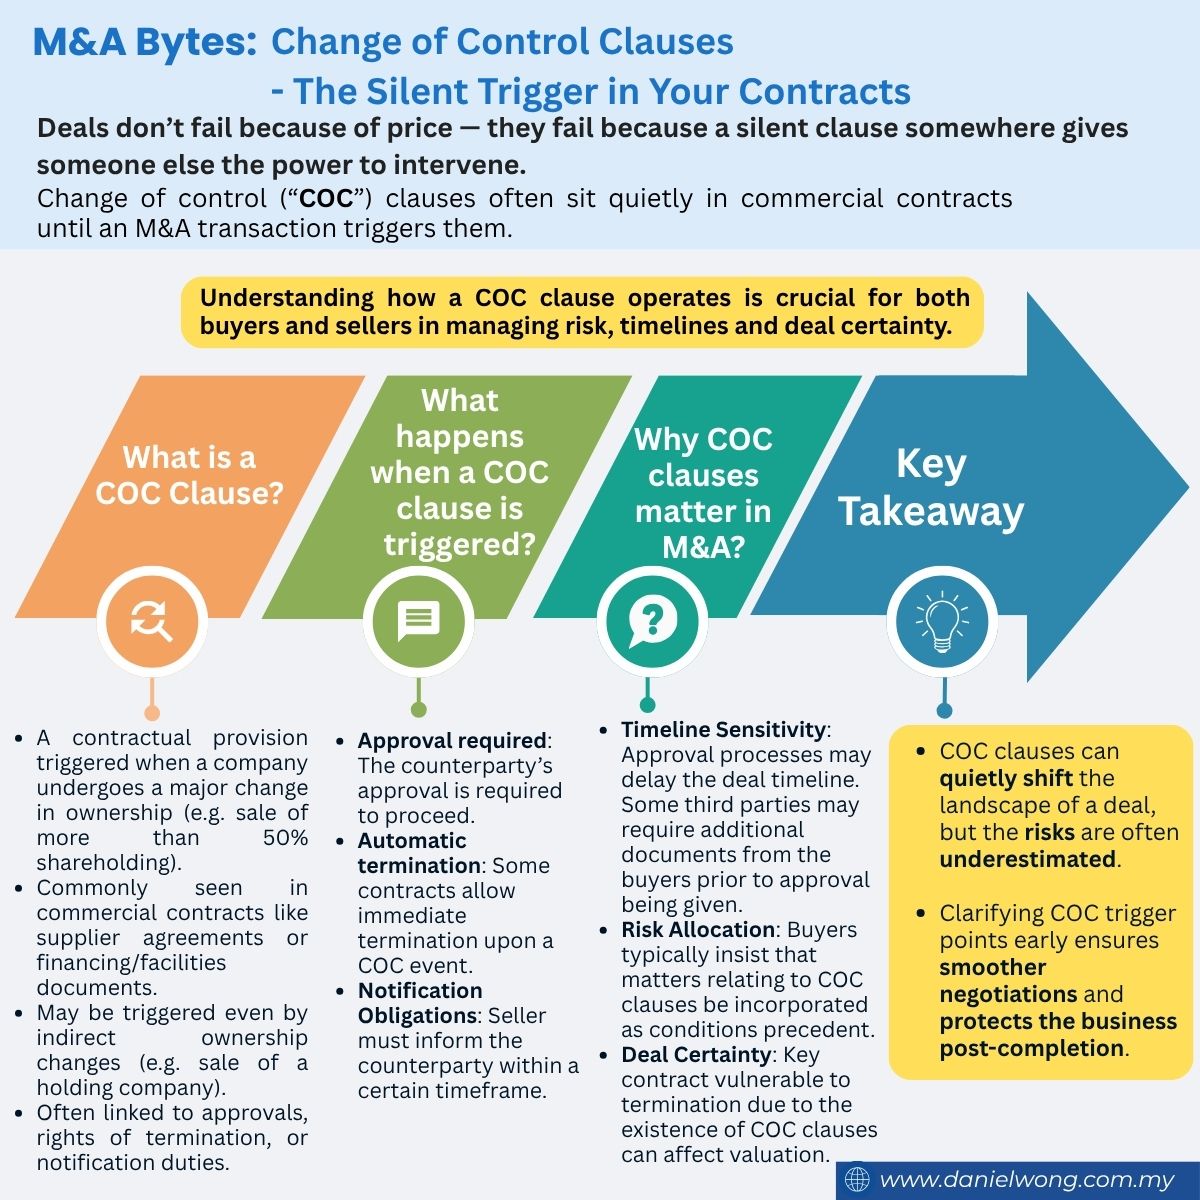
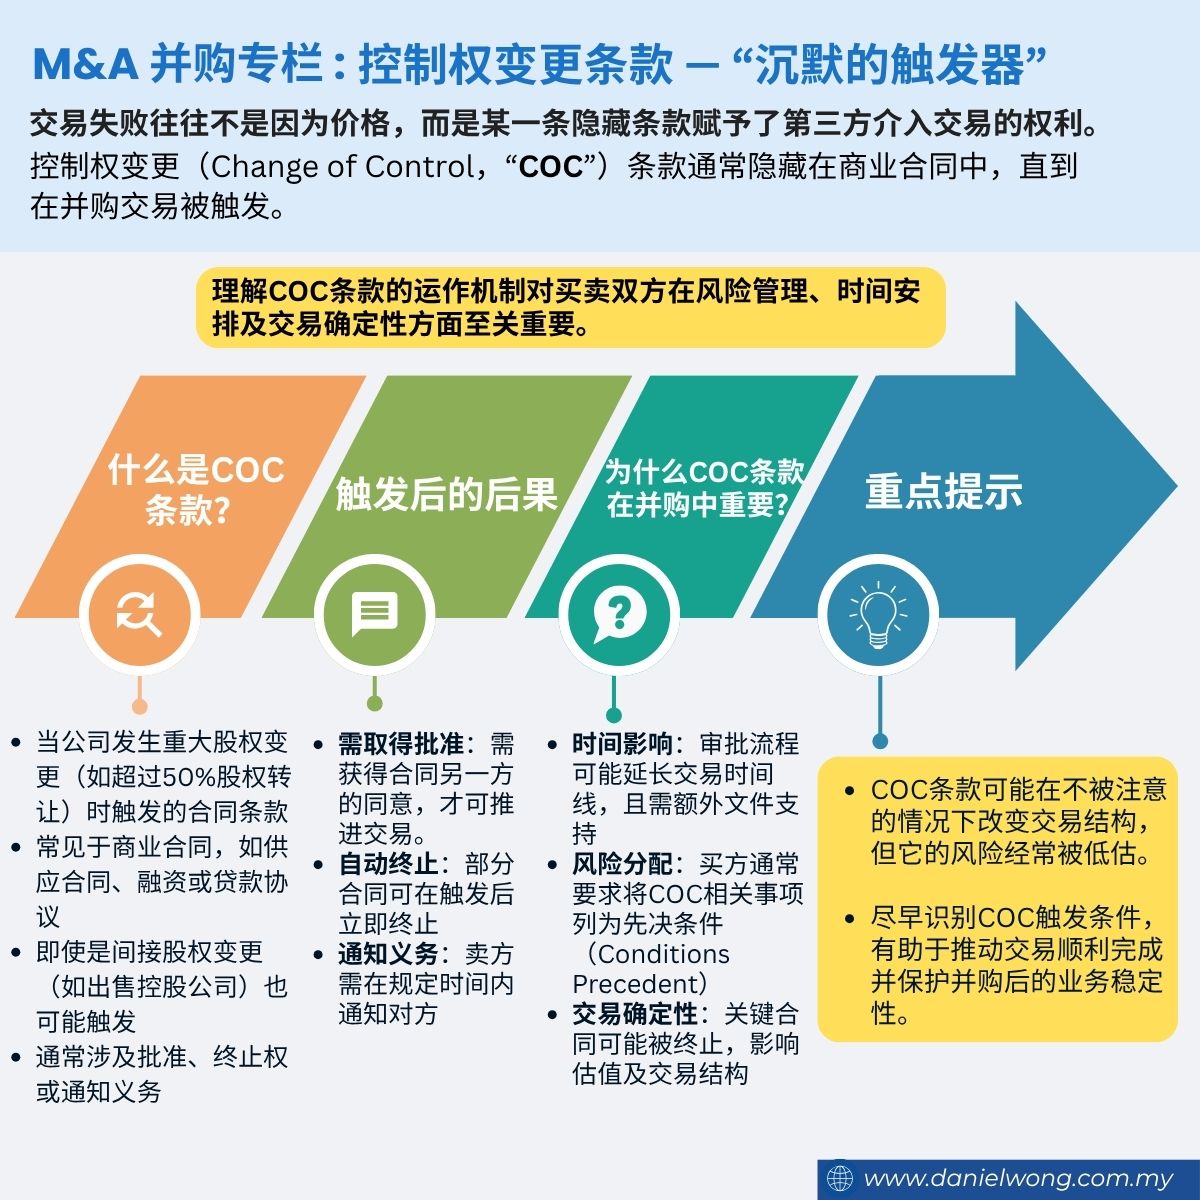
Deals don’t fail because of price – they fail because a silent clause somewhere gives someone else the power to intervene.
Change of control (“COC”) clauses often sit quietly in commercial contracts until an M&A transaction triggers them.
Understanding how a COC clause operates is crucial for both buyers and sellers in managing risk, timelines and deal certainty.
What is a COC clause?
- A contractual provision triggered when a company undergoes a major change in ownership (e.g. a sale of more than 50% shareholding).
- Commonly seen in commercial contracts like supplier agreements or financing/facilities documents.
- May be triggered even by indirect ownership changes (e.g. a sale of a holding company).
- Often linked to approvals, rights of termination, or notification duties.
What happens when a COC clause is triggered?
- Approval required: The counterparty’s approval is required to proceed.
- Automatic termination: Some contracts allow immediate termination upon a COC event.
- Notification Obligations: The seller must inform the counterparty within a certain timeframe.
Why COC clauses matter in M&A?
- Timeline Sensitivity: Approval processes may delay the deal timeline. Some third parties may require additional documents from the buyers prior to approval being given.
- Risk Allocation: Buyers typically insist that matters relating to COC clauses be incorporated as conditions precedent.
- Deal Certainty: Key contracts vulnerable to termination due to the existence of COC clauses can affect valuation.
🔑 Key Takeaway:
COC clauses can quietly shift the landscape of a deal, but the risks are often underestimated.
Clarifying COC trigger points early ensures smoother negotiations and protects the business post-completion.
In Essence:
Disclaimer: The content of this article is intended for general informational purposes only and does not constitute formal legal advice.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- September 8, 2026
NVIDIA has agreed to acquire Hugging Face, a leading open AI platform used by more than 18 million developers and over 200,000 companies worldwide, for approximately US$12.9 billion. The proposed acquisition marks a significant expansion of NVIDIA’s footprint beyond AI hardware and further into the software and developer ecosystem, giving it ownership of a platform hosting millions of AI models, datasets and applications.
From a strategic standpoint, the deal strengthens NVIDIA’s position across the AI chain and reinforces its investment in open AI development. At the same time, NVIDIA’s acquisition of a platform valued for its open access and cross-platform compatibility raises competition and platform-neutrality considerations, with NVIDIA committing that Hugging Face will continue to support different models, frameworks, cloud providers and computing platforms – including those outside NVIDIA’s ecosystem.
Taken together, the proposed acquisition demonstrates the strategic value of controlling critical infrastructure across the AI chain, while highlighting the competition and regulatory considerations that may arise when a dominant technology player acquires a widely used open platform.


🌏 Our Global Deal Radar series highlights major M&A deals and corporate transactions shaping industries worldwide. Follow us for monthly insights.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- August 26, 2026
Deals don’t fail because of price; they fail because someone else hasn’t said yes. Are all your approvals in place?
One overlooked approval can stall – or even sink – an otherwise well-negotiated deal.
In many M&A transactions, third-party approvals are one of the most underestimated hurdles. Whether from regulators, landlords, banks, or key customers, these approvals can materially affect the deal timeline, risk allocation, and even price negotiations.
What are third-party approvals?
- Approvals required from parties outside the buyer and the seller.
- Often tied to contracts entered into by the target company, licences, financing documents or regulatory requirements.
- Frequently a “must have” when a change of control occurs.
Typical third-party approvals in Malaysian M&A
- Regulator approvals:g. MCMC, MITI, local councils – where the validity of licences is impacted.
- Landlord approvals: Required for tenancies/leases containing change-of-control clauses.
- Bank approvals: Commonly required for financing documents restricting assignment or change of shareholders.
- Key customer approvals: Particularly where contracts are exclusive or high-value.
Why it matters for the deal?
- Affects timelines – additional steps required to procure third-party approvals, resulting in a prolonged deal timeline.
- Affects risk allocation – buyers typically want procurement of third-party approvals as Conditions Precedent (“CP”), while sellers prefer to limit CP.
- Affects certainty – failure to obtain third-party approvals may delay completion or even trigger renegotiation.
🔑 Key Takeaway:
Third-party approvals are more than procedural – they directly impact deal timing, risk, and commercial certainty. Spotting them early through legal due diligence helps prevent avoidable delays and keeps the deal moving.
In Essence:


Disclaimer: The content of this article is intended for general informational purposes only and does not constitute formal legal advice.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- August 11, 2026
Overview
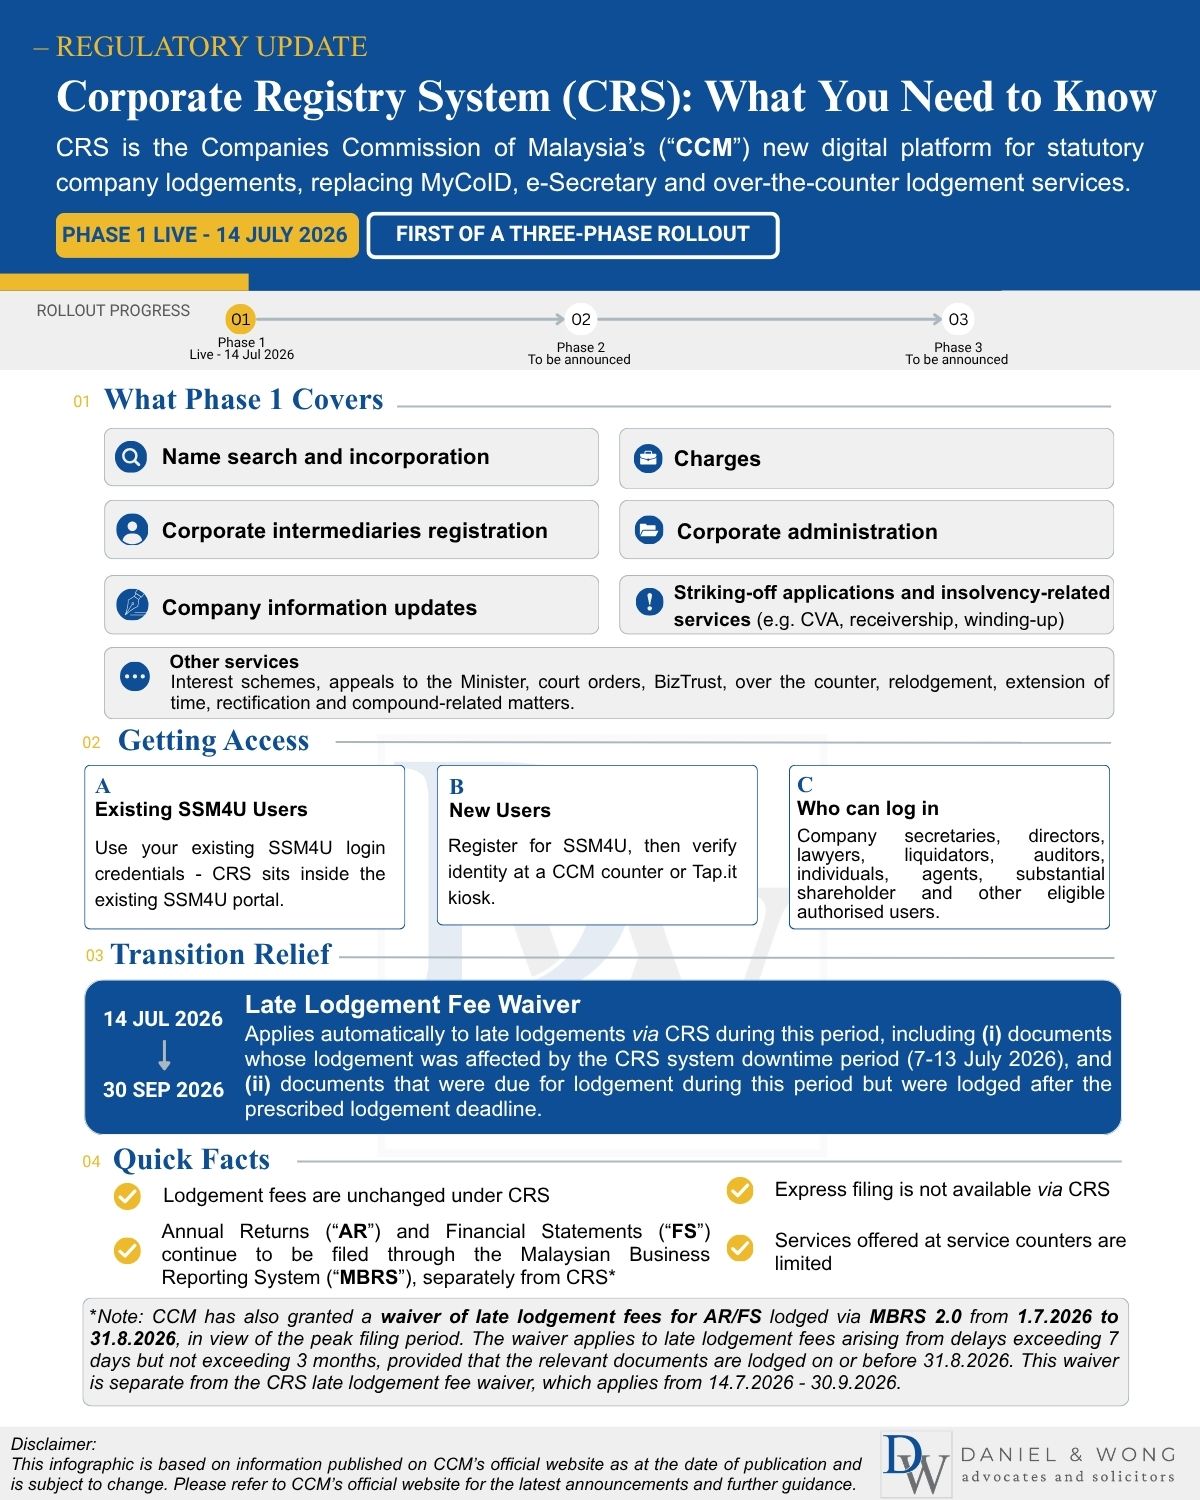
The Corporate Registry System (CRS) is the Companies Commission of Malaysia’s (“CCM“) new digital platform for statutory company lodgments. It replaces previous systems including MyCoID, e-Secretary, and traditional over-the-counter lodgment services.
Phase 1 of the rollout officially went live on 14 July 2026, marking the first phase of a broader three-phase rollout.
What Phase 1 Covers
Phase 1 encompasses 22 services, including:
- Incorporation & Names: Name search and company incorporation
- Corporate Secretarial & Administration: Corporate intermediaries registration, corporate administration, and company information updates
- Charges: Registration and management of charges
- Insolvency & Striking-Off: Striking-off applications and insolvency-related services (including Corporate Voluntary Arrangements, Receivership, Asset Management, Judicial Management, and Winding-Up)
- Other Services: Interest schemes, appeals to the Minister, court orders, BizTrust, over-the-counter services, relodgements, applications for extension of time (EOT), rectifications, and compound-related matters.
Accessing the CRS Portal
A – Existing SSM4U Users
You can log in using your existing SSM4U credentials. The CRS module is integrated directly within the existing SSM4U portal.B – New Users
You must first register for an SSM4U account, then complete an identity verification at a CCM counter or a Tap.it kiosk.
C – Who can log in
Access is permitted for authorised representatives, including:
- Company secretaries
- Directors
- Lawyers
- Liquidators
- Auditors
- Individuals
- Agents
- Susbtantial shareholders
Transition Relief: Late Lodgement Fee Waiver
To facilitate a smooth transition, CCM has introduced an automatic late lodgement fee waiver:
- Waiver Period: 14 July 2026 – 30 September 2026
- Applicability: The waiver applies automatically to eligible late lodgements made via CRS during this period, including:
- Documents whose lodgement was impacted by the CRS system downtime period (i.e., 7 July 2026 – 13 July 2026).
- Documents that were due for lodgement during this period but lodged after the prescribed statutory deadline.
🔑 Quick Facts :
- Lodgement Fees: Lodgement fees remain unchanged under the CRS.
- Express Filing: Express filing services are not available through CRS.
- Counter Services: Services offered at the physical CCM service counters are now limited.
- Annual Returns (“AR”) & Financial Statements (“FS”): AR and FS continue to be filed separately via the Malaysian Business Reporting System (“MBRS“).*
*Note on MBRS 2.0 Fee Waiver: In view of the peak filing period, CCM has separately granted a waiver of late lodgement fees for AR and FS lodged via MBRS 2.0 from 1 July 2026 to 31 August 2026. This applies to late lodgement fees arising from delays exceeding 7 days but not exceeding 3 months (provided documents are lodged on or before 31 August 2026). This waiver is separate from the general CRS late lodgement fee waiver.
In Essence:
Disclaimer: The article is based on information published on the CCM’s official website as of the date of publication and is subject to change. Kindly refer to the CCM’s official website here for the latest announcements and further guidelines.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- July 28, 2026
When it comes to completing a deal, timing isn’t just about the date – it is about the conditions.
Do you know the difference between what must happen before closing, and what can happen after?
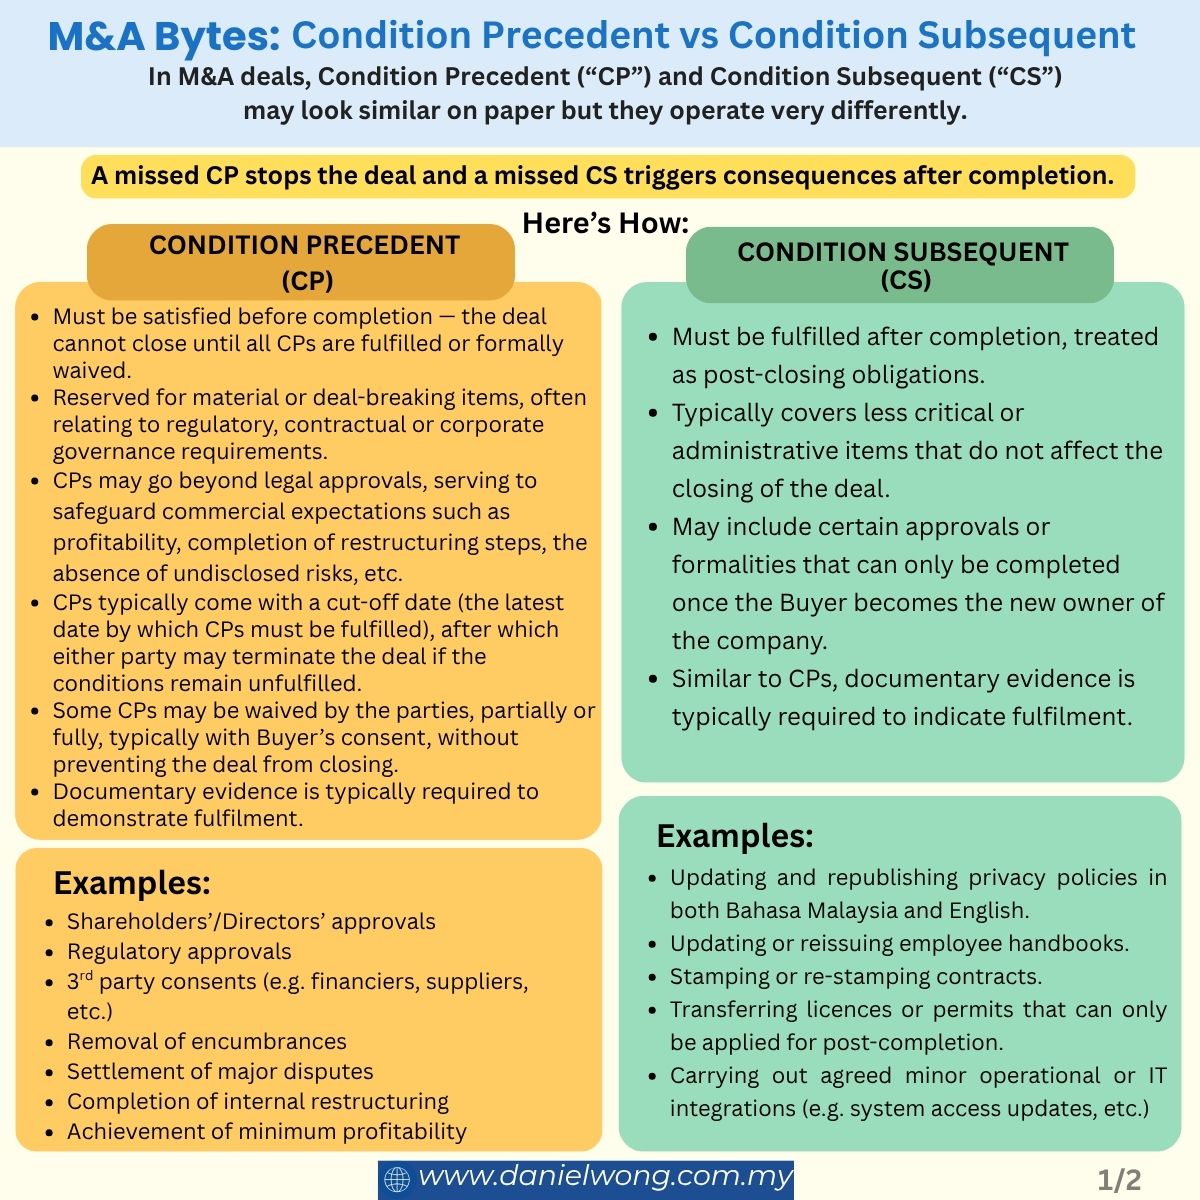
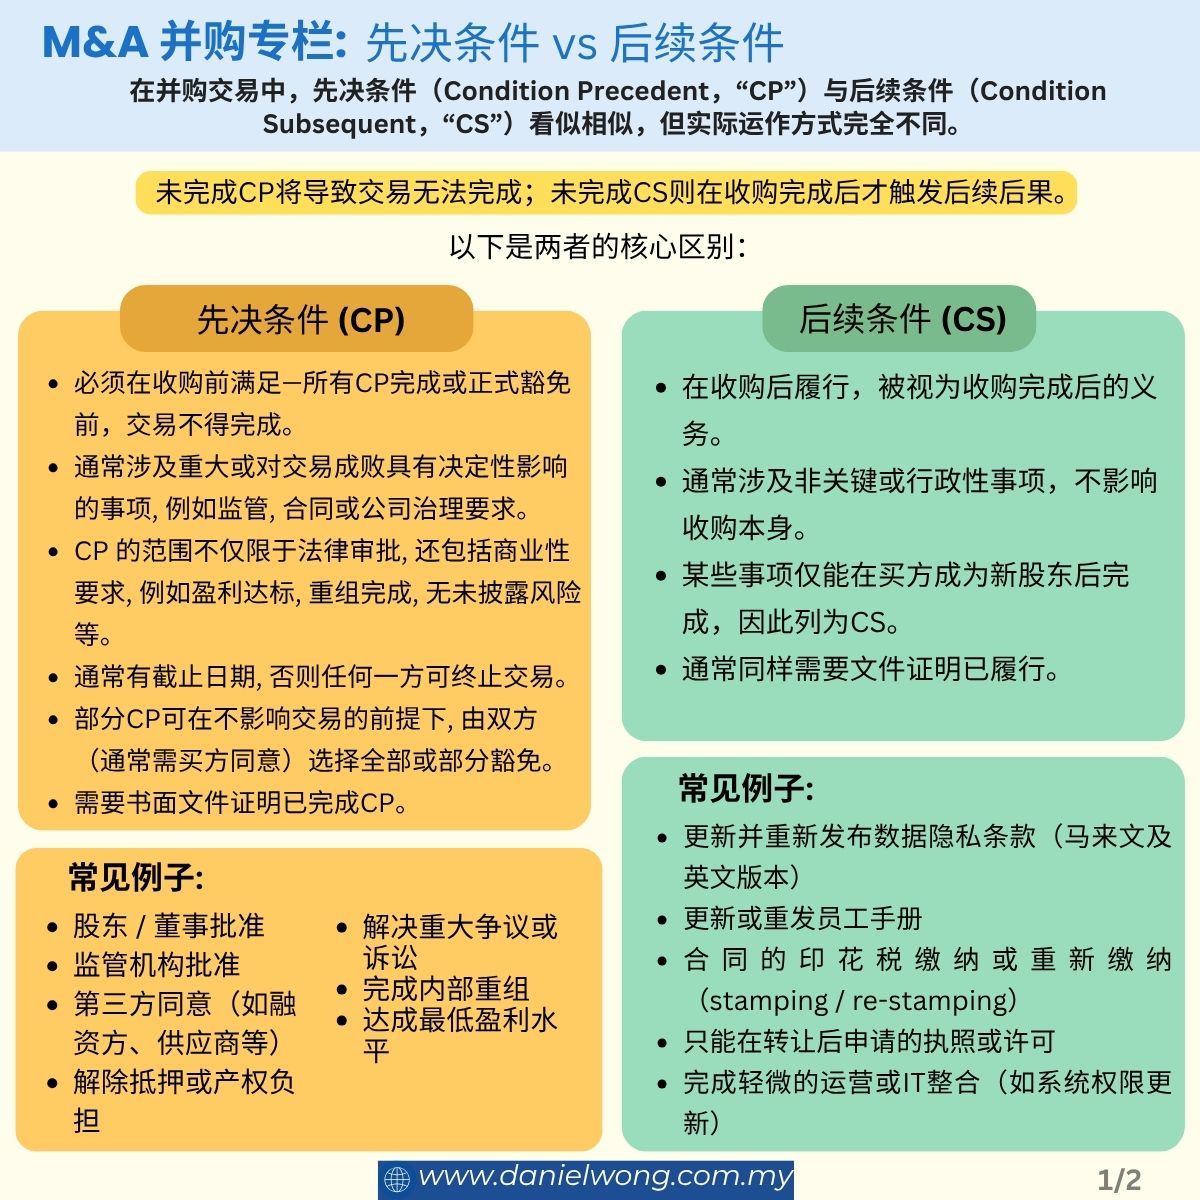
In M&A deals, Condition Precedent (“CP”) and Condition Subsequent (“CS”) may look similar on paper, but they operate very differently. A missed CP stops the deal, and a missed CS triggers consequences after completion.
Find out how these conditions impact your M&A transactions.
What are Conditions Precedent?
Condition Precedent
Conditions Precedent (“CP“) exist to ensure, amongst others, that the essential approvals, financial clean-ups, housekeeping matters, restructurings and third-party consents are completed before the buyer is locked in.In essence, CP:- Must be satisfied before completion – the deal cannot close until all CPs are fulfilled or formally waived.
- Reserved for material or deal-breaking items, often relating to regulatory, contractual or corporate governance requirements.
- CPs may go beyond legal approvals, serving to safeguard commercial expectations such as profitability, completion of restructuring steps, the absence of undisclosed risks, etc.
- CPs typically come with a cut-off date (the latest date by which CPs must be fulfilled), after which either party may terminate the deal if the conditions remain unfulfilled.
- Some CPs may be waived by the parties, partially or fully, typically with Buyer’s consent, without preventing the deal from closing.
- Documentary evidence is typically required to demonstrate fulfilment.
Examples
- Shareholders’ / Directors’ approvals
- Regulatory approvals
- Third-party consents (e.g financiers, suppliers, etc.)
- Removal of encumbrances
- Settlement of major disputes
- Completion of internal restructuring
- Achievement of minimum profitability
Repercussions if not fulfilled
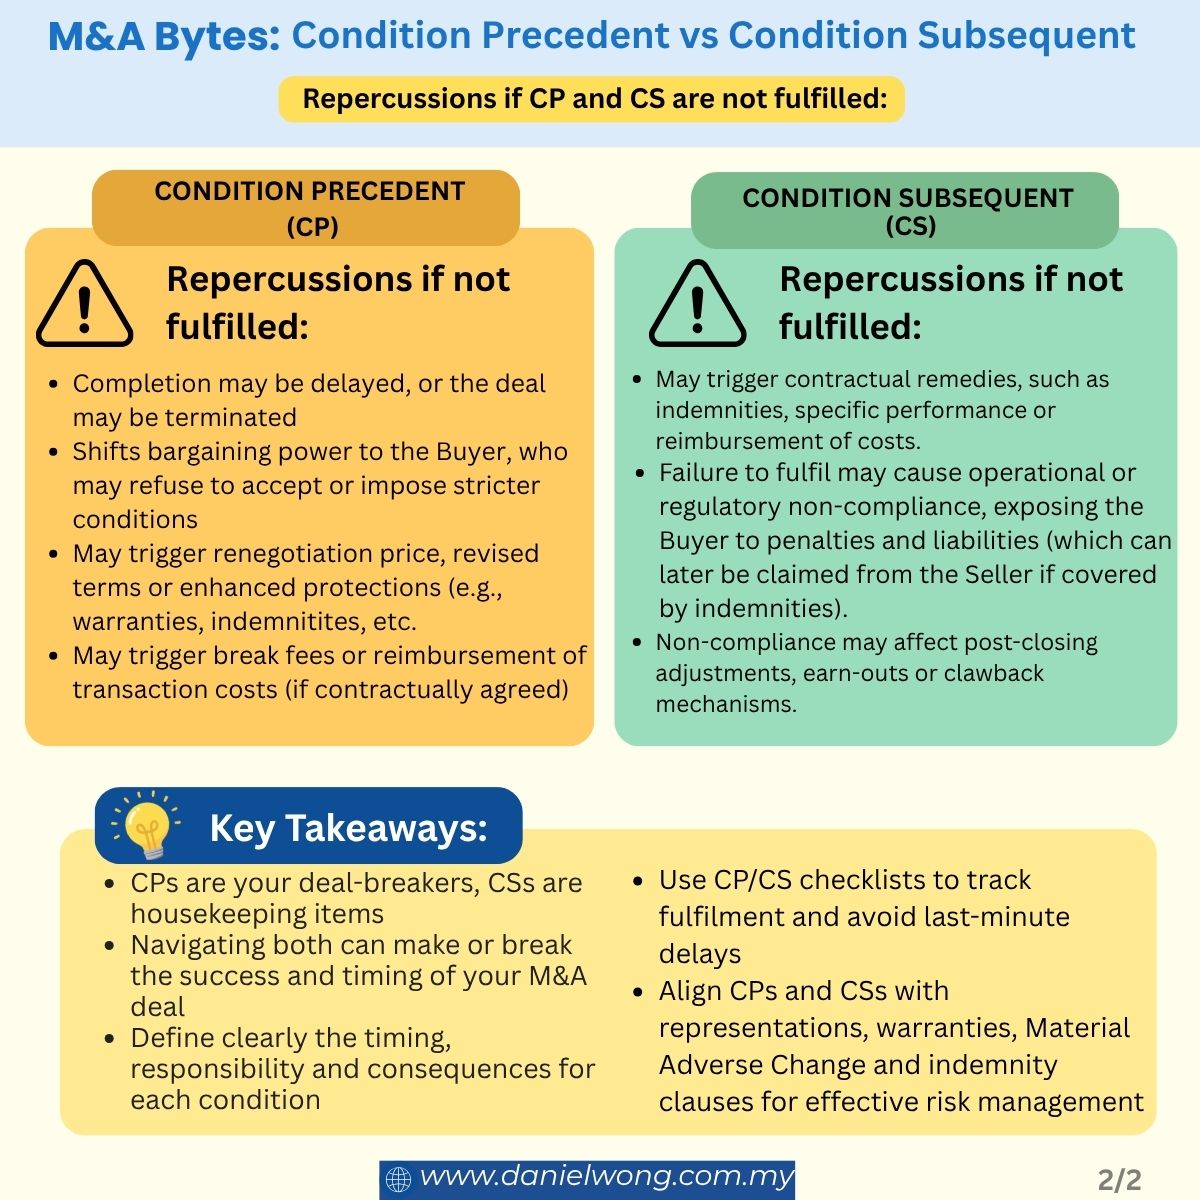
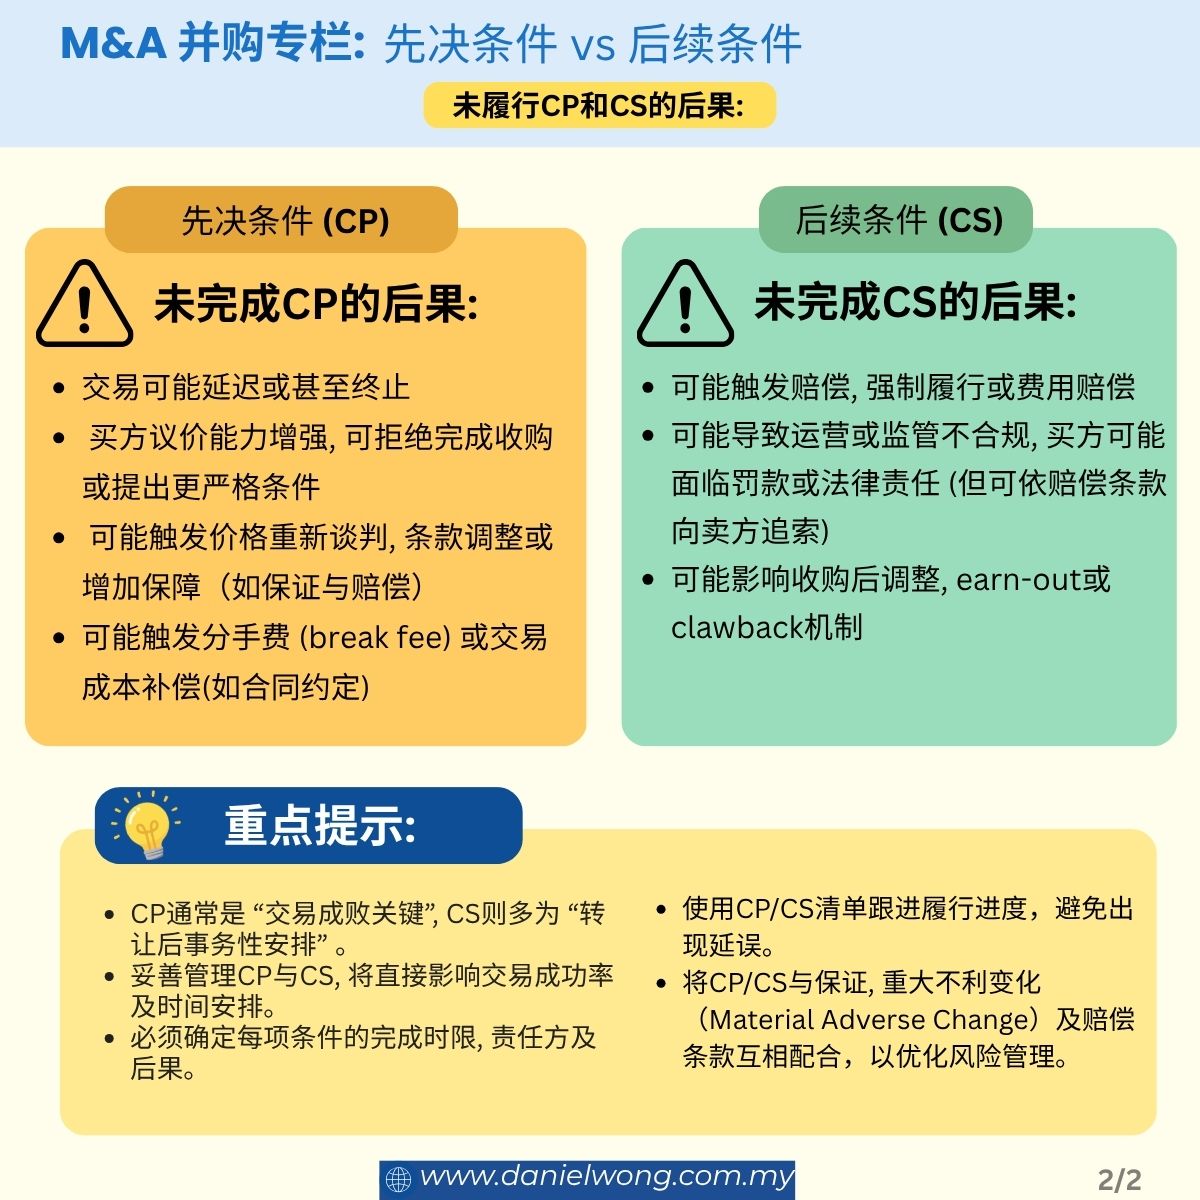
- Completion may be delayed, or the deal may be terminated.
- Failure to fulfil CPs often shifts bargaining power to the Buyer, who may refuse to accept or impose stricter conditions.
- May trigger renegotiation of price, revised terms or enhanced protections (e.g. warranties, indemnities, etc.).
- In some cases, non-fulfilment may trigger break fees or reimbursement of transaction costs (if contractually agreed).
What are Conditions Subsequent?
Condition Subsequent
Conditions Subsequent (“CS“) are future, uncertain events that occur after the deal has closed and can cancel or undo the existing agreement if they fail to happen.In essence, CS:- Must be fulfilled after completion, treated as post-closing obligations.
- Typically covers less critical or administrative items that do not affect the deal’s closing.
- May include certain approvals or formalities that can only be completed once the Buyer becomes the new owner of the company.
- Similar to CPs, documentary evidence is typically required to indicate fulfilment.
Examples
- Updating and republishing privacy policies in both Bahasa Malaysia and English.
- Updating or reissuing employee handbooks.
- Stamping or re-stamping contracts.
- Transferring licences or permits that can only be applied post-completion.
- Carrying out agreed minor operational or IT integrations (e.g. system access updates, etc.)
Repercussions if not fulfilled
- May trigger contractual remedies, such as indemnities, specific performance or reimbursement of costs.
- Failure to fulfil may cause operational or regulatory non-compliance, exposing the Buyer to penalties and liabilities (which can later be claimed from the Seller if covered by indemnities).
- Non-compliance may affect post-closing adjustments, earn-outs or clawback mechanisms.
🔑 Key Takeaway:
- CPs are mostly your deal-breakers, and CSs are most likely your housekeeping items.
- Navigating CPs and CSs can make or break the success and timing of your M&A deal.
- Parties should clearly define the timing, responsibility and consequences for each condition.
- Use CP / CS checklists to track fulfilment and avoid last-minute delays.
- Align CPs and CSs with representations, warranties, MAC and indemnity clauses for effective risk management.
In Essence:
Disclaimer: The content of this article is intended for general informational purposes only and does not constitute formal legal advice.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- July 15, 2026
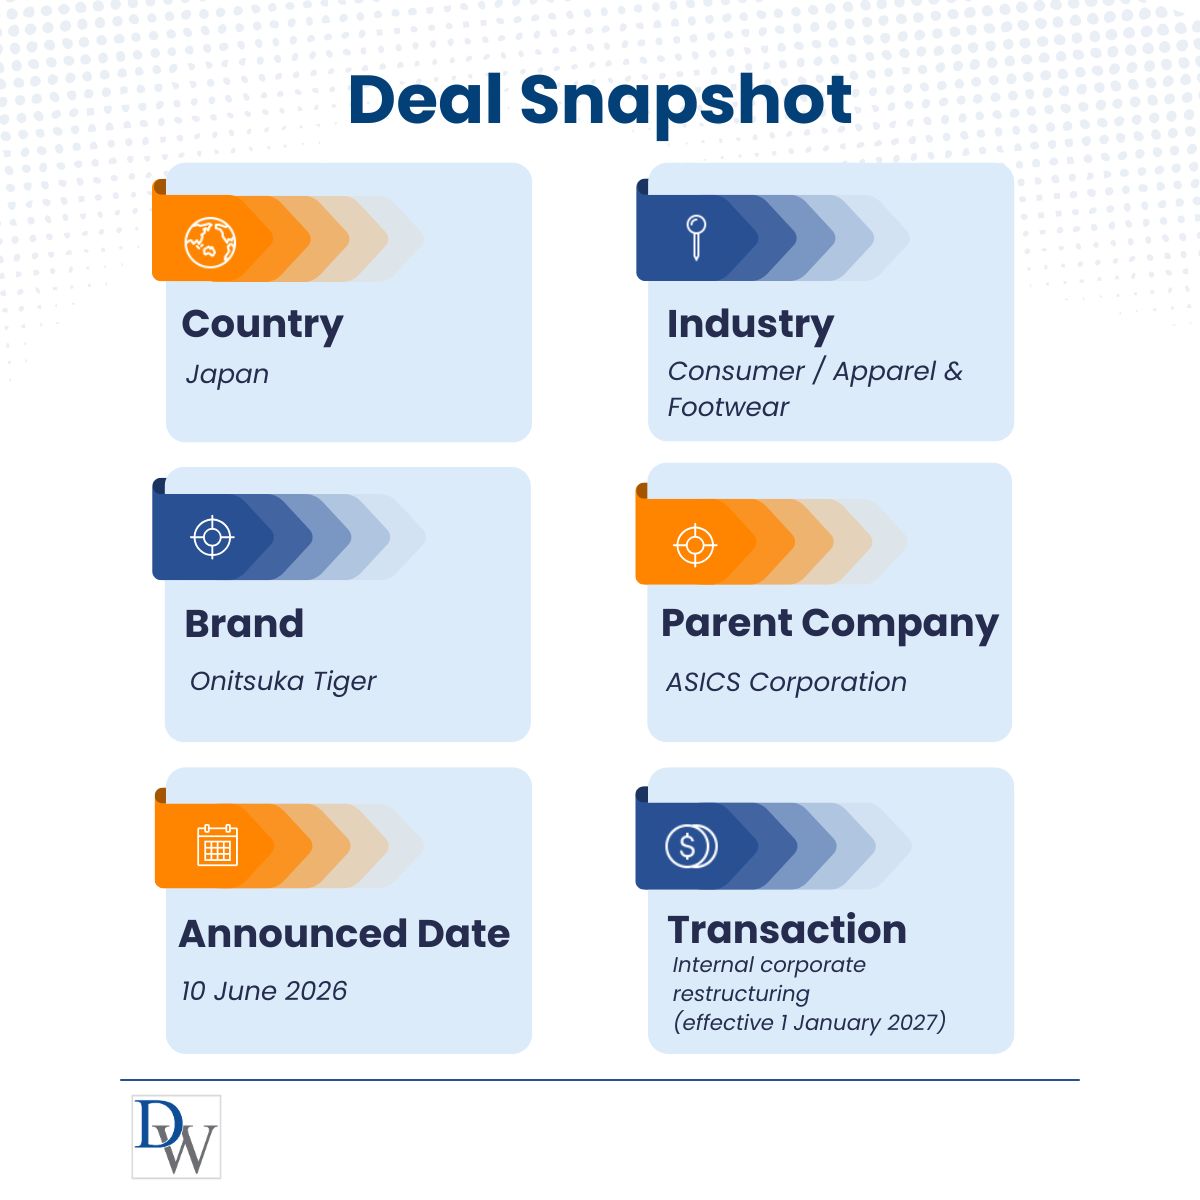
ASICS Corporation has announced plans to separate its high-growth lifestyle brand Onitsuka Tiger into a standalone, wholly owned subsidiary, OT GROUP, with the reorganisation expected to take effect on 1 January 2027. Despite the separation, ASICS will remain the sole shareholder of OT GROUP, with the restructuring aimed at streamlining decision-making and strengthening Onitsuka Tiger’s global competitiveness.
From a strategic standpoint, the reorganisation reflects a growing trend among multinational groups to separate high-performing business units into dedicated entities, enabling greater operational autonomy while retaining ownership. Such carve-out structures can sharpen brand positioning, enhance management focus and provide greater strategic flexibility for future corporate actions. This can also be seen as part of a risk management strategy.
Taken together, these developments highlight how corporate restructurings can be as significant as traditional M&A transactions in unlocking value, improving governance, risk allocation and positioning businesses for long-term growth.
🌏 Follow us for monthly insights as our Global Deal Radar series highlights major M&A deals shaping industries worldwide.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- June 30, 2026
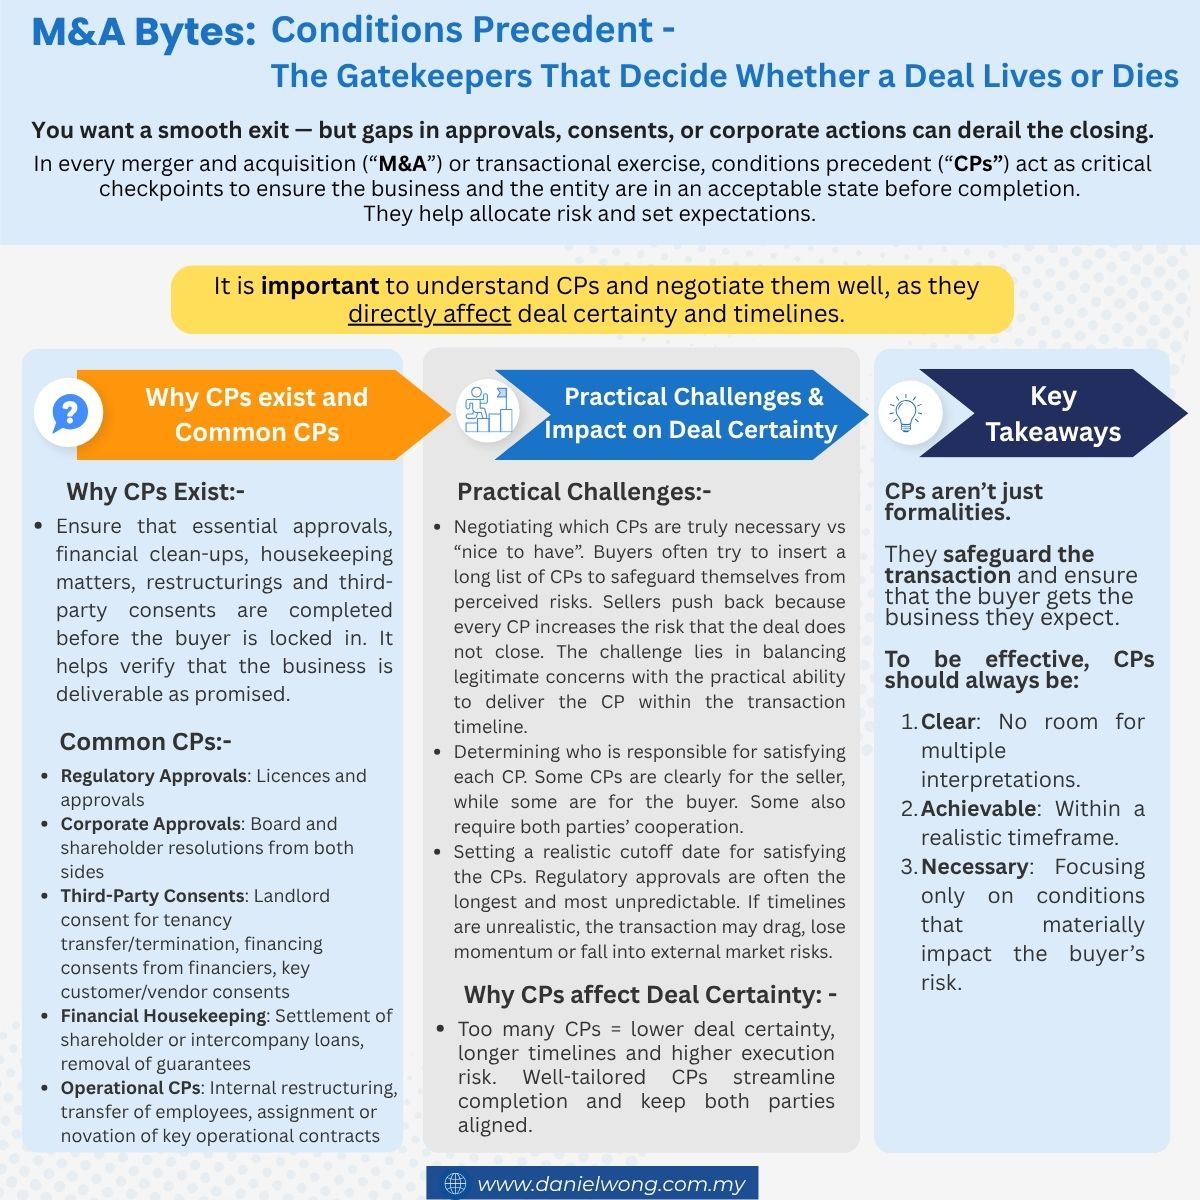
You want a smooth exit – but gaps in approvals, consents, or corporate actions can derail the closing.
In every merger and acquisition (“M&A”) or transactional exercise, conditions precedent (“CPs”) act as critical checkpoints to ensure the business and the entity are in an acceptable state before completion. They help allocate risk and set expectations.
It is important to understand CPs and negotiate them well, as they directly affect deal certainty and timelines.
Why CPs exist and Common CPs
CPs exist to ensure that essential approvals, financial clean-ups, housekeeping matters, restructurings and third-party consents are completed before the buyer is locked in. It helps verify that the business is deliverable as promised.Common CPs include:- Regulatory Approvals: Licences and approvals
- Corporate Approvals: Board and shareholder resolutions from both sides
- Third-Party Consents: Landlord consent for tenancy transfer or termination, financing consents from financiers, key customer or vendor consents
- Financial Housekeeping: Settlement of shareholder or intercompany loans, removal of guarantees
- Operational CPs: Internal restructuring, transfer of employees, assignment or novation of key operational contracts
Practical Challenges & Impact on Deal Certainty
Practical Challenges:-
- Negotiating which CPs are truly necessary vs “nice to have”.
- Buyers often try to insert a long list of CPs to safeguard themselves from perceived risks. Sellers push back because every CP increases the risk that the deal does not close.
- The challenge lies in balancing legitimate concerns with the practical ability to deliver the CP within the transaction timeline.
- Determining who is responsible for satisfying each CP.
- Some CPs are clearly for the seller, while some are for the buyer. Some also require both parties’ cooperation.
- Setting a realistic cutoff date to satisfy the CPs.
- Regulatory approvals are often the longest and most unpredictable. If timelines are unrealistic, the transaction may drag on, lose momentum or face external market risks.
Why CPs affect Deal Certainty:-
- Too many CPs can lower deal certainty. This, in turn, would result in longer timelines and higher execution risks.
- Thus, well-tailored CPs would streamline completion and keep both parties aligned.
🔑 Key Takeaway:
CPs aren’t just formalities. They safeguard the transaction and ensure that the buyer gets the business they expect.
To be effective, CPs should always be:
- Clear: Leaves no room for multiple interpretations.
- Achievable: To be negotiated within a realistic timeframe.
- Necessary: Focusing only on conditions that materially impact the buyer’s risk.
In Essence:
Disclaimer: The content of this article is intended for general informational purposes only and does not constitute formal legal advice.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
- June 16, 2026
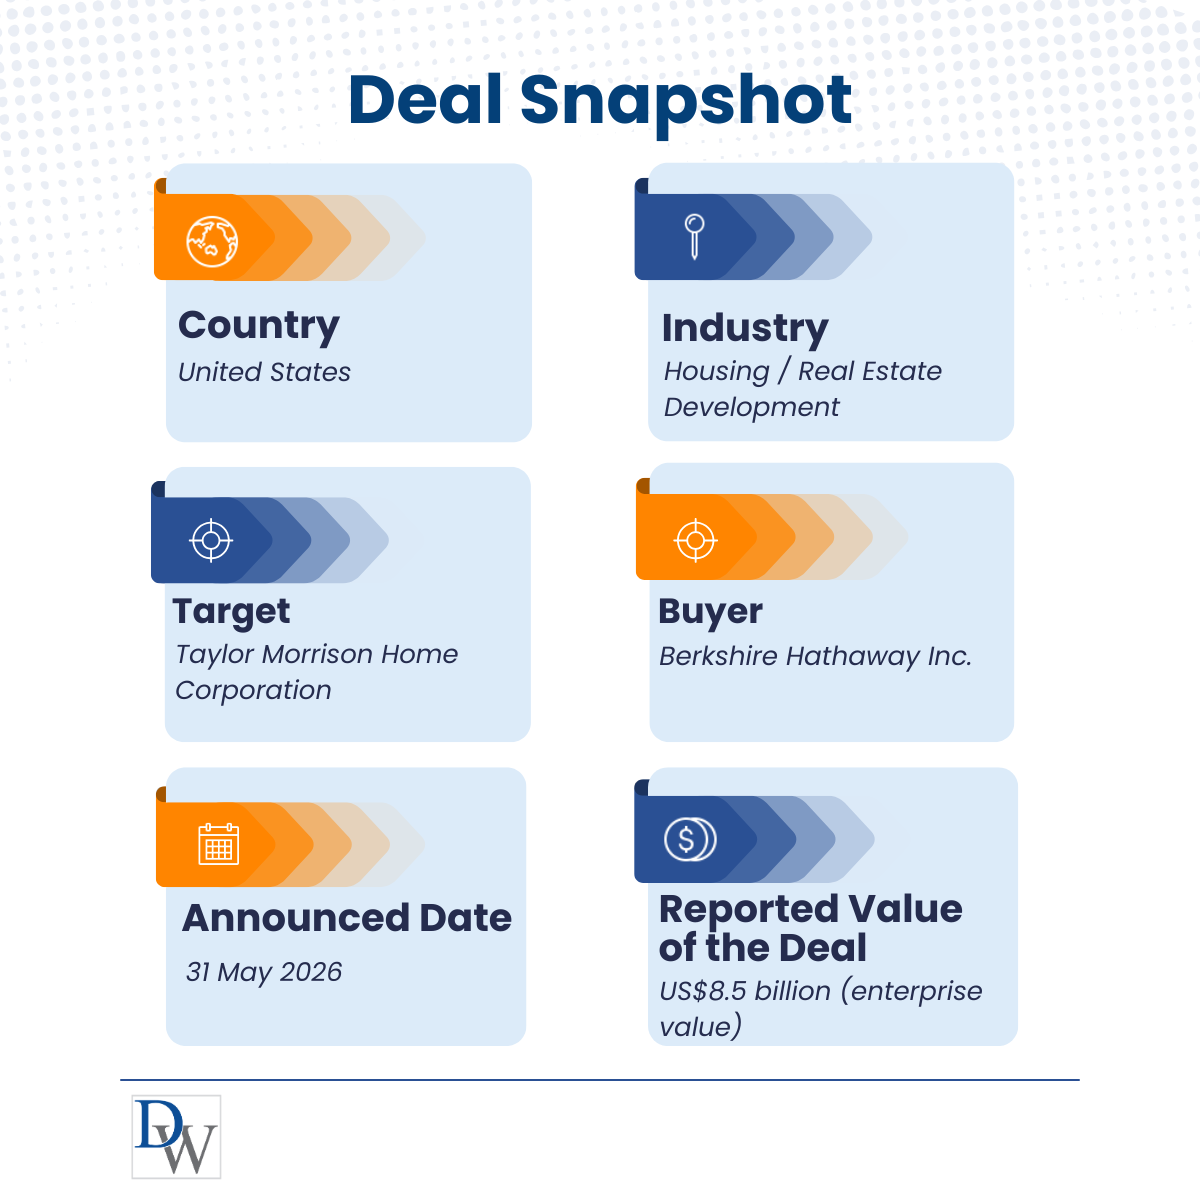
Berkshire Hathaway has announced its proposed acquisition of Taylor Morrison Home Corporation, one of the largest homebuilders in the United States, in an all-cash transaction valued at approximately US$8.5 billion. The deal marks the first major acquisition under Berkshire’s new Chief Executive Officer, Greg Abel, and reflects Berkshire’s continued commitment to the US housing market.
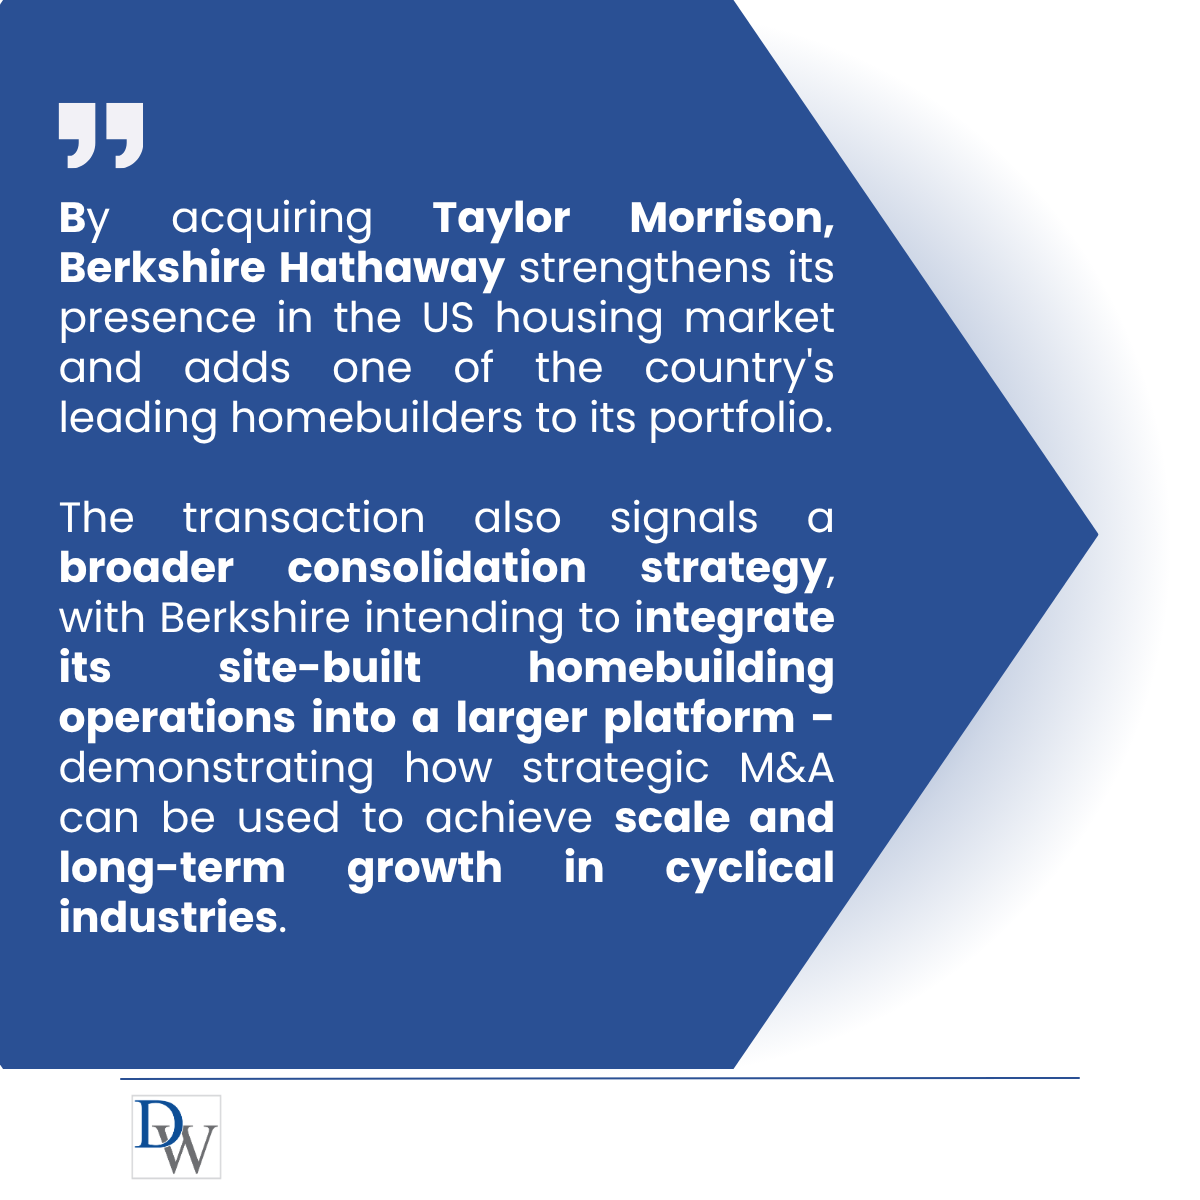
Beyond expanding Berkshire’s housing portfolio, the transaction is expected to complement its existing housing and building products businesses. Notably, Berkshire has indicated in its announcement that it intends to eventually unify its site-built homebuilding operations into a combined platform, signalling a strategic move towards greater scale and operational integration in the sector.
Taken together, this deal demonstrates how strategic acquisitions can be deployed to strengthen market position during cyclical downturns, while highlighting the role of long-term capital in driving consolidation within mature industries.
🌏 Follow us for monthly insights as our Global Deal Radar series highlights major M&A deals shaping industries worldwide.
Our Corporate team regularly advises local and international corporations on mergers and acquisitions (M&A), cross-border transactions, joint ventures, and corporate restructuring. We also provide comprehensive support for shareholders’ agreements and general commercial advisory to help businesses navigate the Malaysian regulatory landscape.
For legal assistance or further inquiries regarding your corporate matters, please feel free to contact us.
